All Categories
Featured

Choosing the 2026 Medicare Advantage Plan
That versatility can be substantial if your income changes from year to year, or you go through a huge life event (such as divorce or momentary work leave) and still wish to keep your policy in force. It also implies you'll require to pay closer attention to your policy over time.
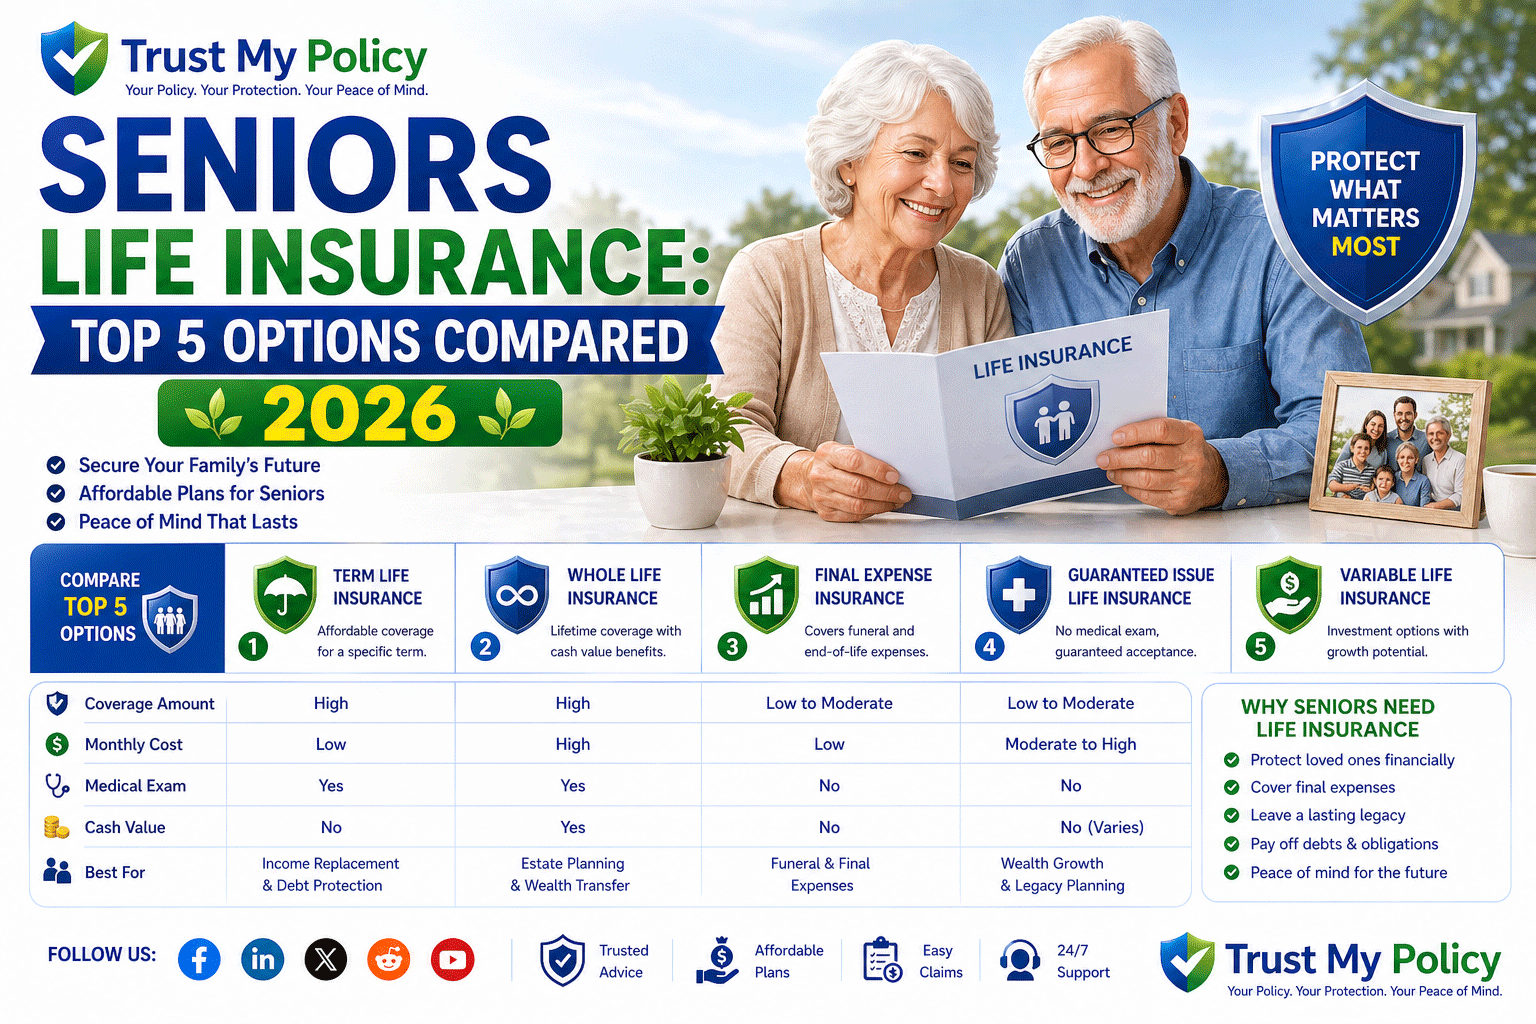
This table highlights the biggest differences: Both entire life insurance coverage and indexed universal life provide you with irreversible coverage that builds money value, but how that money value grows is rather various. Whole life insurance coverage normally has actually guaranteed development at a set rate, while IUL has the potential for higher returns since its cash value is tied to a market index.
Term life insurance coverage is typically the most economical and easiest kind of life insurance coverage to get. It doesn't develop money value, but you get a guaranteed survivor benefit for a set period of time, typically at a fraction of the cost of an IUL policy. You can consider a variable universal life insurance coverage policy as one step above an IUL policy in regards to threat and benefit.
Common Annuity MythsThis means you'll have higher development capacity but likewise the possibility of investment losses. Like any financial product, indexed universal life insurance coverage has advantages and trade-offs. If your main goal is just replacing your earnings for your household, a term life insurance policy is generally easier and far less costly.

How IUL Benefits Secure Retirement
Common costs might consist of:, which normally increases as you age for handling the policy deducted from your payments if you include features like long-lasting care or persistent illness benefits if you cancel the policy throughout its early years Before you buy an indexed universal life policy, the insurance provider will typically offer an illustration revealing how your policy could perform gradually.

Latest Posts

Affordable Plan Choices for Veterans
Comparing Term and Whole Life Insurance Strategies
2026 Whole Life Insurance Prices for Families