All Categories
Featured


How Whole Life Insurance Functions
Table of Contents
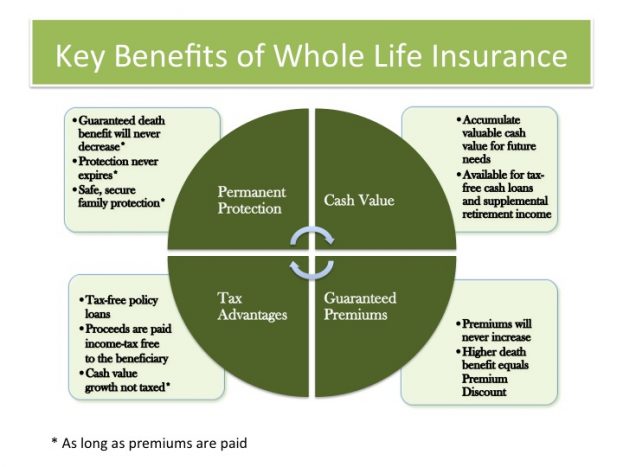
As soon as the first premium is paid, the whole death benefit is set aside for your household. Earnings tax-free death benefit: The death advantage of a life insurance coverage policy is not typically subject to federal income taxes. Tax-deferred development: The development of money value inside of whole life insurance coverage is tax-deferred while the funds stay in the policy.
This indicates withdrawals to the degree of expense basis are thought about an earnings tax-free return of cost basis. Tax-favorable access to cash value loans for any reason: During the insured's life, cash value loans taken against a whole life policy are not thought about to be a taxable event, even though the policy might have a big gain in excess of premiums paid.
Self-funding: The policy can pay for itself over time by applying dividends to pay premiums, which contributes to the policy's cost savings part. Impairment protection: An entire life policy can continue to be moneyed even if you are disabled. When you choose the Waiver of Premium rider9, if you suffer a qualifying disability, your policy will continue to provide death advantage security, have money value growth, and pay dividends even while you aren't paying premiums.
10Distribution: If properly carried out, life insurance helps avoid probate and can provide recipients with higher personal privacy than may be paid for by a will; a will ends up being public once probated, whereas death benefit circulations are normally private, contractually driven transactions. When a policy loan has been taken, the annual dividend can be utilized to help pay back the policy loan.
Features, arrangements, and costs vary from one insurance provider to the next, and each entire life agreement is unique to the insurance policy holder. Entire life insurance rates depend upon factors such as age, health, and coverage quantity, so it's essential to consider these when evaluating policies. Typically speaking, there are two basic kinds of payment structures for whole life: Level premium whole life: This is the most common kind of entire life insurance coverage.
Insurance in Irvine CAMedicare Part D Coverage and Drug Tips
Restricted payment whole life: This type of policy has a fixed level premium like a level premium whole life policy, however the premium is just payable for a set amount of time. The advantage is that they are guaranteed to be paid up at the end of the payment duration, so no payment is required at later ages.
Their availability and cost depends upon the policy and the insurance company. In addition to the Waiver of Premium rider pointed out above, some other options offered by Guardian consist of: Paid-Up Additions Rider: The PUA rider can help increase the accumulation of tax-deferred money values and death advantage. The greater the premium paid into the rider, the higher the protection paid for by the policy.
It gives you a special opportunity for index-linked upside capacity and the flooring ensures that your year-to-year drawback market direct exposure is limited. Accidental Death Benefit: Supplies an extra death benefit if death takes place by accidental bodily injury. Accelerated Benefit Rider: Supplies accelerated advantages, allowing you to access a portion of the death advantage early if you are detected with a persistent or terminal health problem.
Final Expense and Burial Expense Planning
Guaranteed Insurability Choice (GIO): Gives the policy owner the right to acquire extra insurance coverage without evidence of insurability. The GIO can become a lot more important in the event of disability: A guaranteed who is handicapped and has their premium waived might work out the GIO rider, and Guardian will pay the premium on the brand-new policy An entire life insurance coverage policy is one of the most crucial monetary purchases you can make.
12 Comparing life insurance coverage companies and their life insurance coverage offerings such as entire life, universal life, fixed premiums, ensured death advantages, and cash value growth is vital to finding the ideal policy for your needs. There are reputable, independent sources for financial strength rankings, such as A.M. Best, Moody's, Requirement & Poor's and Fitch.

Discuss your scenario with an insurance expert or monetary expert who comprehends whole life insurance coverage and can direct you to the service that best fulfills your needs. If you don't know such a professional, ask a friend or coworker for a suggestion.
A whole life policy has money value that grows over time. You can cash it out to assist supplement retirement, or obtain versus it at any time, for any factor. Whole life policies have a component described as the policy's cash worth: A portion of your premium dollars can grow gradually on a tax-deferred basis, so you don't pay taxes on the gains.

Latest Posts
Getting Fast Individual Life Insurance Quotes

Low-Cost Health Quotes for US Veterans

Top Medigap Plans