All Categories
Featured

Choosing PPO vs HMO Insurance Plans
A whole life insurance coverage policy in an extremely literal sense is more than just life insurance coverage. It's a versatile monetary instrument that helps protect households and organizations from uncertainty while assisting them construct and enhance wealth. If that is very important to you, this article can assist address essential questions, including: Whole life insurance coverage is, primarily, irreversible life insurance coverage security that lasts your whole life; by contrast, term life insurance only covers you for a specific variety of years.
Insurance in Lakewood CAWhole life insurance coverage policies also have a "money worth" component a life-long monetary possession. 1 Because life insurance defense is considered advantageous to society, it has actually been offered tax advantages you might not discover with many other financial instruments.
Then, based on your life expectancy, the insurance provider's actuaries set 4 ensured values4: A guaranteed level premium: Entire life insurance coverage policies have fixed premiums that are guaranteed never ever to alter. As long as you keep making exceptional payments, the policy will remain in impact, and each premium payment adds to the policy's money worth.
A surefire cash value: A cash worth that is guaranteed to grow at a set rate each year until it amounts to the face amount of the policy at a specified age, usually age 100 or 121. A guaranteed endowment: The death benefit is guaranteed to be paid if the insured is still living at the age defined in the contract, usually age 100 or 121. A part of each premium payment is allocated to a cash value account, which grows in time.
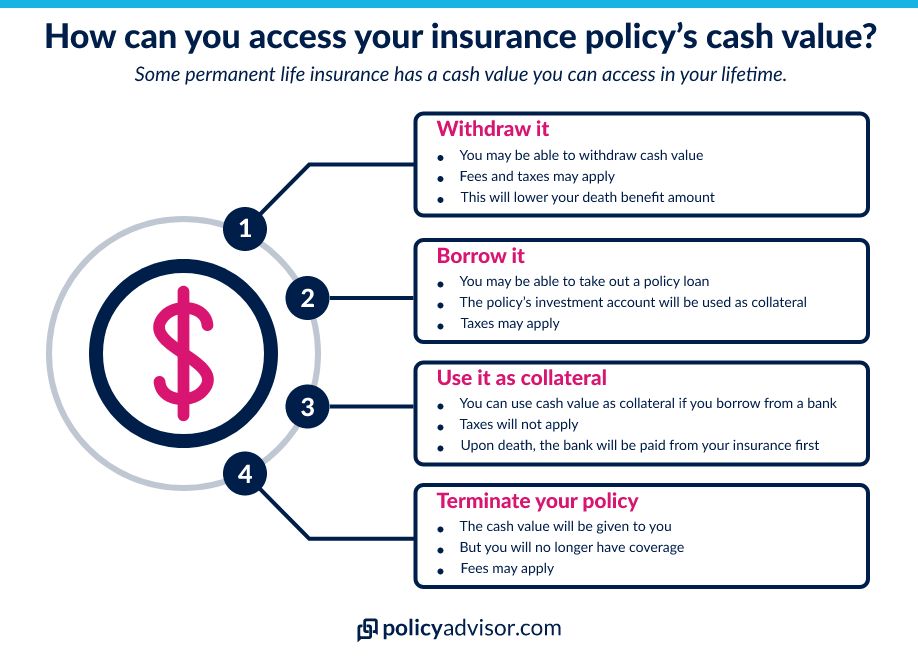
It can take time for it to turn into a helpful quantity, however once that occurs, you can obtain money against your policy's cash value, use it to pay premiums, or even surrender it for cash in retirement. 5If you purchase entire life from a mutual insurance provider, such as Guardian, the cash value portion can also make annual dividends, which can increase your money worth beyond the guaranteed rate. While there's no guarantee that dividends will be declared each year, Guardian has paid them every year considering that 1868, even during wars, pandemics, or stock exchange turbulence. Depending upon your needs, you can decide to use your dividends in different methods. One choice is to buy paid-up additions (PUAs).7 A PUA is guaranteed irreversible, paid-up life insurance coverage.
Life Insurance Strategies for Veteran Families
Over time, the intensifying accumulation of PUAs can help to offset the effects of inflation by providing a greater death benefit and cash value. Dividend build-ups can likewise be withdrawn earnings tax-free, up to the policy basis (i.e., the amount of premiums paid to date).
It can also supply a number of other financial advantages. The majority of people see the importance of insuring the worth of residential or commercial property, such as their home or car, so they buy casualty insurance. The human life value8 of a specific one of the most important possessions of a family or business is also insurable.
The survivor benefit of life insurance can assist guarantee the economic connection of a household when it is faced with the death of an enjoyed one, by helping supply funds that can be utilized for: Payment of a mortgageEducation fundingIncome needsTime away from work to care for household needsFuneral expenses Outstanding debts Companies aiming to create a service connection strategy in case of the death of a partner or key employee have unique insurance coverage needs.
Life insurance coverage can assist address four major areas of business methods: The financing of buy-sell agreements and stock redemption plansThe funding of extra retirement programsKey individual indemnificationPayment of loans and home mortgages Planning for the orderly transfer of residential or commercial property at death can assist to minimize taxes and offer heirs in a manner that shows your desires.
It can allow the policy owner to use estate possessions in methods that might not be possible otherwise. For example, it can be the "approval slip" that lets you use other aspects of your retirement income and individual net worth. It can give you the power to spend assets that might not otherwise be utilized.

Latest Posts
Finding Affordable 2026 Family Health Insurance
Individual Medical Insurance Quotes for 2026
Choosing PPO vs HMO Insurance Plans